Buy now pay later moves a purchase into the cart today and puts the payments on the bank’s calendar for the weeks that follow. Federal Reserve survey data show who ends up paying late and what it costs them in fees and overdrafts, while a CFPB study of lender records shows how often one borrower holds several plans at once. The arithmetic of how those debits stack comes between the two.
Table of Contents
Who Uses Buy Now Pay Later and Who Pays Late
The Federal Reserve’s 2025 household survey, fielded in October 2025 and published in May 2026, asked adults whether they had used buy now, pay later (BNPL) in the prior 12 months. Sixteen percent had used it, up from 10 percent in 2021. The table splits use, late payment and motive by family income.
| Family income | Used BNPL (all adults) | Paid late (among users) | Main reason: only way to afford it (among users) |
|---|---|---|---|
| Under $25,000 | 18% | 40% | 40% |
| $25,000 to $49,999 | 23% | 33% | 37% |
| $50,000 to $99,999 | 18% | 25% | 32% |
| $100,000 or more | 12% | 11% | 15% |
| All adults or users | 16% | 26% | 29% |
Use peaks in the $25,000 to $49,999 band, while lateness climbs as income falls. Users with family income under $25,000 paid late more than three times as often as users at $100,000 or more. In the top bracket the most common reasons were wanting to spread out payments (38 percent) and avoiding interest (26 percent).
Black and Hispanic adults were more than twice as likely as White or Asian adults to use BNPL, and the survey reports that sizeable differences remain after controlling for income and age.
How Biweekly Debits Stack in a Checking Account
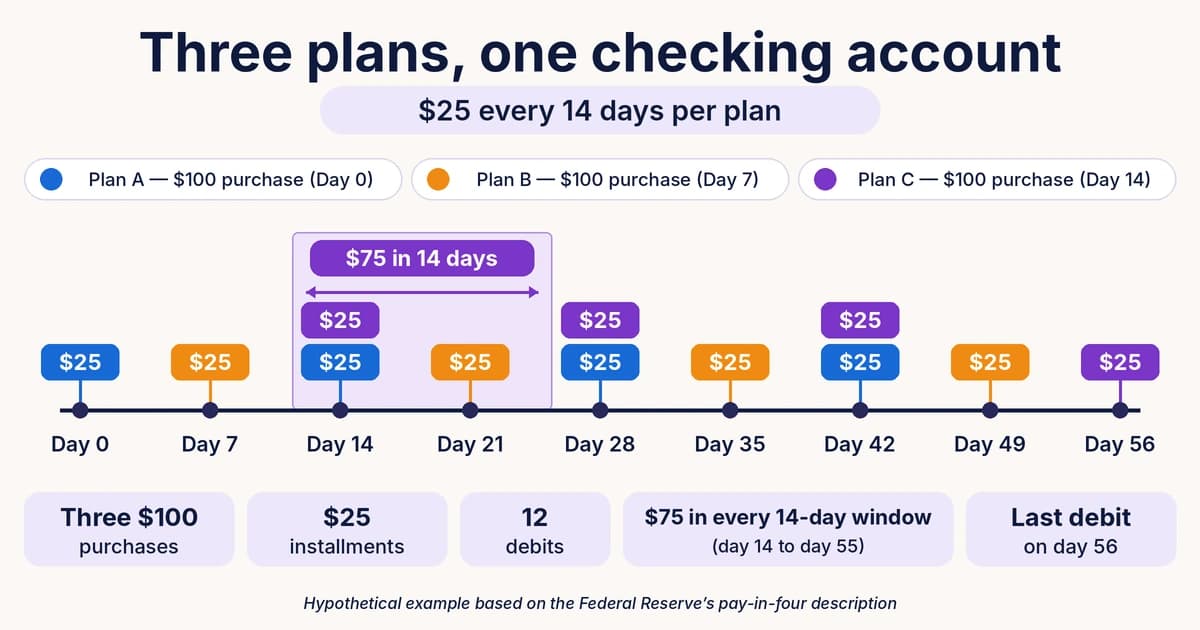
A typical plan, as the Federal Reserve illustrates it, starts with a $100 item: $25 at checkout and three more $25 payments two weeks apart. Because most users must enroll in automatic payments, many installments are pulled straight from a checking account on fixed dates.
A plan’s installment is the price divided by four, repeated every 14 days. Adding the installments of every active plan gives the amount that leaves the account in each 14-day cycle. To see it, take three hypothetical $100 purchases made on days 0, 7 and 14. The debits fall on days 0, 7, 14 (twice), 21, 28 (twice), 35, 42 (twice), 49 and 56. From day 14 through day 55 each 14-day window carries $75, and $200 of the $300 total leaves after the last purchase. The figure to hold against a checking balance is that 14-day sum, compared with the lowest balance expected before the next paycheck.
A biweekly schedule has 26 debit dates a year, and two months carry three debits per plan in place of two. Budgets built on monthly figures tend to miss those months.
The same survey ties autopay to bank fees. Eleven percent of BNPL users had a payment trigger an overdraft or non-sufficient funds (NSF) fee in the prior year. Of users who paid late, 64 percent said they were charged extra, and among those charged extra, 38 percent also had an overdraft or NSF fee set off by a BNPL payment.
When installments and card minimums compete for the same cash, Three Credit Cards, One Extra Payment: Which Gets It compares the order of payoff.
What the CFPB Found About Overlapping Loans
In January 2025 the CFPB released a study of BNPL borrowers that matched loan records from six large pay-in-four lenders with credit records. The page is archived and the data describe 2022, which makes the findings a pattern in that year’s market and not a current total.
The CFPB counted 63 percent of borrowers originating multiple simultaneous loans at some point in 2022, and 33 percent borrowing from more than one lender. About 20 percent were heavy users who started more than one loan a month on average, and the average number of originations per borrower rose from 8.5 to 9.5.
Credit cards sat in the same picture. BNPL borrowers held higher balances on other unsecured debt, cards included, and average card utilization rose before a first BNPL loan, which the CFPB says suggests that less available card credit may push consumers toward BNPL. Approval was easy, with lenders approving 78 percent of loans to applicants with subprime or deep subprime scores.
Readers who carry a card balance alongside installments can see how the interest arithmetic works in Credit Card Balance Growing Despite Payments.
What These Reports Cannot Tell You
The two sources measure different things. Survey answers record what adults report of their own experience, so late payments and fees are self-reported. The CFPB data come from lender records, but they cover six firms and stop at 2022.
The agency also notes that lenders do not typically report BNPL loans to nationwide consumer reporting companies, so total borrowing is hard to see.
Neither source reports the size of a typical installment. The $25 payments above come from the Federal Reserve’s own example, and terms differ by provider. Zero-interest offers on credit cards follow a separate fee and payment schedule, worked out in 0% Balance Transfer Math.
Frequently Asked Questions
Does BNPL help build credit?
When the survey was fielded, BNPL purchases and on-time payments did not affect credit histories or scores at any of the three major bureaus. Yet 53 percent of users wrongly agreed that on-time payments help their score, and only 14 percent answered both of the survey’s credit questions correctly. Check your provider’s current reporting policy.
What do people buy with it?
Close to half of users bought clothing and accessories with BNPL at least once in the prior year, and electronics and furniture or appliances were also common. One in five used it for groceries or food delivery, and 45 percent of those users said it was the only way they could afford the purchase.
Why choose it over a credit card?
The most common main reason was spreading out payments, at 31 percent, followed by affordability. Avoiding interest was the main reason for 16 percent, convenience for 12 percent and not wanting to use a credit card for 4 percent.
Which age groups use it most?
Use is highest at ages 18 to 29 (22 percent) and 30 to 44 (21 percent) and falls to 9 percent at 60 and over. The late rate among users follows the same slope, from 32 percent at ages 18 to 29 to 12 percent at 60 and over. In the CFPB data, BNPL made up 28 percent of unsecured debt for borrowers aged 18 to 24 in the months they borrowed, against 17 percent across all ages.
About the Author
Wealth Power is edited by Dilip Kumar Bharati. Articles on U.S. personal finance are researched and drafted with AI assistance using public sources such as IRS data, Bureau of Labor Statistics reports and Federal Reserve publications, and are reviewed and edited by him before publication.
Disclaimer
Disclaimer: This article is for informational and educational purposes only and does not constitute financial, tax, or legal advice. Individual financial situations vary. Readers should consult a qualified financial, tax, or legal professional before making any financial decisions.