In this hypothetical household, COBRA after a layoff costs $1,938 a month once one paycheck disappears. That is $338 more than the $1,600 in unemployment benefits meant to replace it, and the couple ends up $3,608 short every month. The figures are invented to show how the arithmetic works, except the averages and rules that carry a link. This guide walks through that budget, the Department of Labor rules behind it, and a checklist to run before a layoff.
Table of Contents
What Happens to the Budget When One Spouse Loses a Job
One spouse takes home $5,200 a month. The other, who holds the family health plan through an employer, takes home $4,200 after taxes and after the $520 that payroll deducts for the plan. Household income is $9,400. Their monthly bills look like this:
- Mortgage with taxes and insurance escrowed: $3,100
- Childcare: $1,450
- Two car payments: $780
- Car insurance and fuel: $480
- Utilities, phone and internet: $520
- Student loan: $340
- Groceries: $1,100
- Everything else, from clothing to birthday gifts: $700
The bills total $8,470, which leaves $930 of room each month. The cushion is 9.9 percent of take-home pay, and it looks healthy until the plan holder’s last paycheck arrives. Income then falls to $5,200 and the gap opens at $3,270, before any new expense is added. The cushion covers less than a third of it. Payroll deductions like that one are a reason take-home pay trails gross pay, as explained in Take-Home Pay Shrinks as Deductions Expand.
Nobody chose this budget in a single decision. Fixed costs were added one at a time while two paychecks were arriving.
What COBRA After a Layoff Does to the Health Insurance Bill
Suppose the family plan has a full premium of $1,900 a month. The plan holder pays $520 through payroll, 27 percent of the total, and the employer covers the remainder as part of compensation. KFF’s 2026 Employer Health Benefits Survey found that workers contribute an average of $7,471 toward family premiums that total $28,303 a year, or $2,359 a month. Workers’ share works out to 26 percent. Against that, the 27 percent here is close to typical, though this plan is cheaper than average. When the job ends, the employer share ends too, and it was never visible in the payroll deduction.
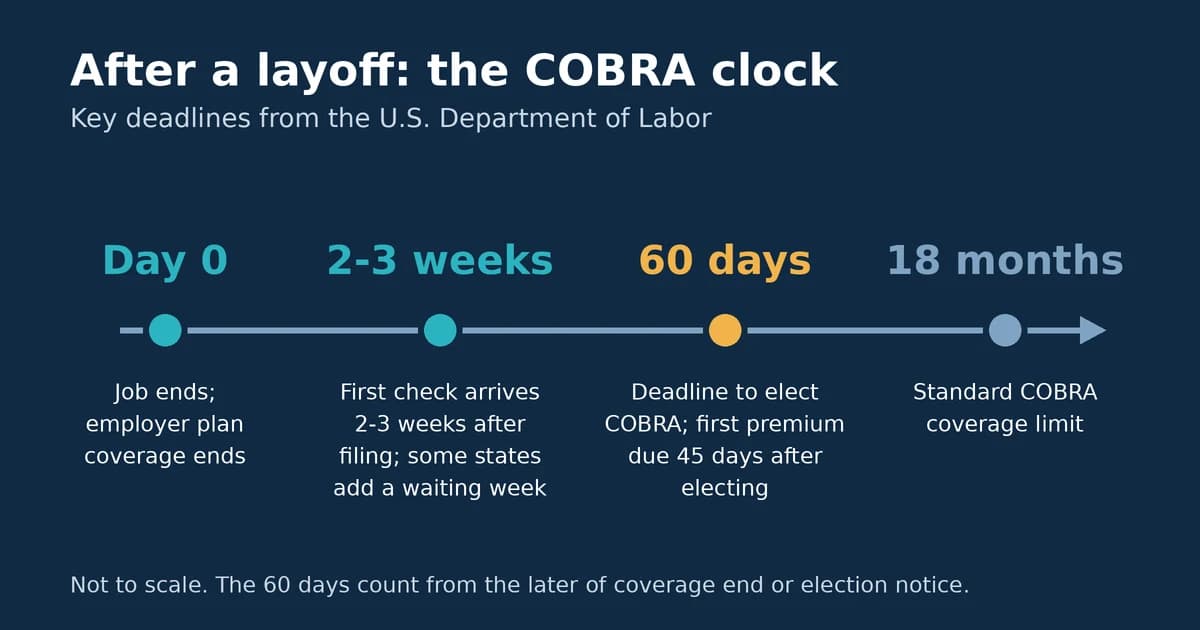
COBRA lets many former employees keep the same group plan, with a price attached. The Department of Labor’s guidance on job loss explains that the plan may charge the entire group premium plus a 2 percent administrative fee, and that coverage lasts up to 18 months. For this family, 102 percent of $1,900 comes to $1,938 a month, a $1,418 jump from what payroll deducted. At the KFF average premium, the same rule would produce $2,406 a month.
Other routes exist. The other spouse’s employer might let the family join that plan, and a marketplace plan is a third option. Costs and doctor networks differ. The first days of a layoff are the time to compare. The Labor Department’s COBRA FAQs allow 60 days to enroll, counted from whichever is later, the end of coverage or the election notice, and 45 days after electing to make the first payment. Any new plan also brings its own deductible, a topic covered in High Deductible Health Plan Upfront Costs.
How Far Unemployment Benefits and Savings Stretch
Unemployment insurance replaces only part of lost pay. The Department of Labor’s fact sheet says benefits are a percentage of earnings over a recent 52-week period, capped at a state maximum, and that they can be paid for up to 26 weeks in most states. Recipients may elect to have tax withheld by the state agency.
Say the plan holder qualifies for $1,600 a month, 38 percent of take-home pay. Household income becomes $6,800 against bills of $10,408: the original $8,470 plus the $1,938 COBRA premium. The monthly shortfall is $3,608. COBRA alone costs $338 more than the entire benefit. That makes the health premium the largest new bill in the household.
With $12,000 in savings, the couple has 3.3 months if benefits start immediately. They seldom do. The same fact sheet says the first check generally arrives two to three weeks after filing, and some states add a one-week waiting period. If the first $1,600 arrived a month late, the first month’s gap would be $5,208 and the same savings would last 2.9 months.
Home equity and retirement balances look large on paper. Turning them into cash takes time and may cost taxes or fees.
Which Bills Can Move and Which Cannot
Bills respond to pressure at different speeds. Groceries and the everyday category total $1,800, or 21 percent of all obligations, and both can change within weeks. Car insurance can be re-shopped, and childcare may shrink if schedules change. The mortgage, the two car loans and the student loan follow contracts that ignore income, though servicers may offer hardship options, and it helps to ask before a payment is missed.
Cutting groceries to $900 and the everyday category to $300 saves $600 a month. The shortfall falls to $3,008 and the savings last four months, two-thirds of a month longer than before. Spending cuts help, yet the movable slice is too small to close the gap alone.
A new job does not end the squeeze at once. The first paycheck may not arrive for weeks, and the new employer’s health plan may not start coverage immediately. A COBRA bill can then overlap with the first stretch of new income.
When the Higher Earner Is the One Who Leaves
Now reverse the story. The $5,200 earner loses a job and the family plan stays with the other spouse’s employer. Income falls to $4,200 against $8,470 of bills, a $4,270 gap that is $1,000 larger than in the first version because that paycheck was bigger. No COBRA premium appears, since health coverage continues unchanged.
Give that spouse a benefit of $1,900 a month, higher than the first benefit because it follows earnings. The shortfall becomes $2,370, and $12,000 lasts 5.1 months. Compare that with the $3,608 shortfall in the first version. With these assumptions, the larger paycheck left the smaller shortfall, because the family health plan stayed in place.
A Short List to Work Through Before It Happens
Each step takes an evening or less, and households that already run short on two paychecks, as described in Why Dual-Income Households Face Paycheck Shortfalls, should start with the first one:
- Ask human resources for the full monthly premium of the family plan, including the employer’s share.
- Read the other spouse’s employer plan rules for adding family members, and note what proof of lost coverage it asks for.
- Find your state’s unemployment agency and write down the weekly maximum and the filing steps, to file the first claim from a checklist.
- Rebuild the budget above with your own numbers and divide cash savings by the monthly shortfall that includes the health insurance bill.
Frequently Asked Questions
Does COBRA apply if hours are cut instead of a layoff?
Yes. Reduced hours are among the events that can qualify, alongside being laid off, quitting or retiring, according to the Labor Department. Being fired for gross misconduct is the exception.
Does everyone in the family have to take COBRA?
No. Spouses and children may enroll even if the former employee does not, and a family member covered elsewhere can simply decline.
Can COBRA last longer than 18 months?
Sometimes. According to the department’s COBRA FAQs, a disability extension adds 11 months, for 29 in total, and a second qualifying event can extend coverage to 36 months. The premium for the added disability months can rise to 150 percent of the plan’s cost, according to the department’s employee guide.
Does a small employer have to offer COBRA?
Federal COBRA covers plans sponsored by employers with 20 or more employees, according to the Labor Department’s COBRA overview. State laws sometimes called mini-COBRA may apply to smaller employers, and the plan administrator can say whether one covers you.
About the Author
Wealth Power is edited by Dilip Kumar Bharati. Articles on U.S. personal finance are researched and drafted with AI assistance using public sources such as IRS data, Bureau of Labor Statistics reports and Federal Reserve publications, and are reviewed and edited by him before publication.
Disclaimer
Disclaimer: This article is for informational and educational purposes only and does not constitute financial, tax, or legal advice. Individual financial situations vary. Readers should consult a qualified financial, tax, or legal professional before making any financial decisions.